President Trump’s Oct. 5 executive order on red-dyed diesel does not repeal the 24.4-cent federal tax on highway diesel. It tells the Treasury Department to stop collecting that tax through Dec. 31, 2026, and to look for ways, including legislation, to cancel the bill afterward.
Until someone finds that way, truckers and farmers are getting a postponed bill, and the tax code is clear about who holds it. In most cases it is the business that sells the dyed fuel, not the driver who burns it. Interstate carriers face a second bill, from the states, that the order does not touch.
What the diesel executive order says
The order, titled Emergency Tax Relief on Diesel Fuel, gives the Treasury secretary five days to decide, in consultation with the secretary of war, whether relief is authorized under section 7508A of the tax code, whether a qualifying event has occurred, and which taxpayers it affected. If he makes those findings, Treasury is to defer the taxes imposed by 26 U.S.C. 4041(a)(1)(A) and 4041(b)(1)(B) that are incurred from Oct. 5 through Dec. 31, 2026, without penalties or interest.
A second directive tells the IRS to announce that it won’t impose the section 6715 penalty when dyed diesel is sold for highway use or burned on the highway during the same window. That penalty is normally the greater of $1,000 or $10 for every gallon involved. Treasury also has to decide how the IRS should handle fuel-tank inspections and fuel sampling while the relief runs, and announce the decision.
The White House fact sheet says truckers will save more than $100 per refill. Agriculture Secretary Brooke Rollins, in a statement the same day, estimated about $640 million in combined federal and state savings across roughly 224.6 million harvested acres, and described the policy as enforcement discretion on road use of dyed diesel. Speaking in Grand Island, Nebraska, before the signing, the president said anyone could now buy the fuel tax-free, Fox Business reported. The signed order says defer.
Who owes the deferred red diesel tax
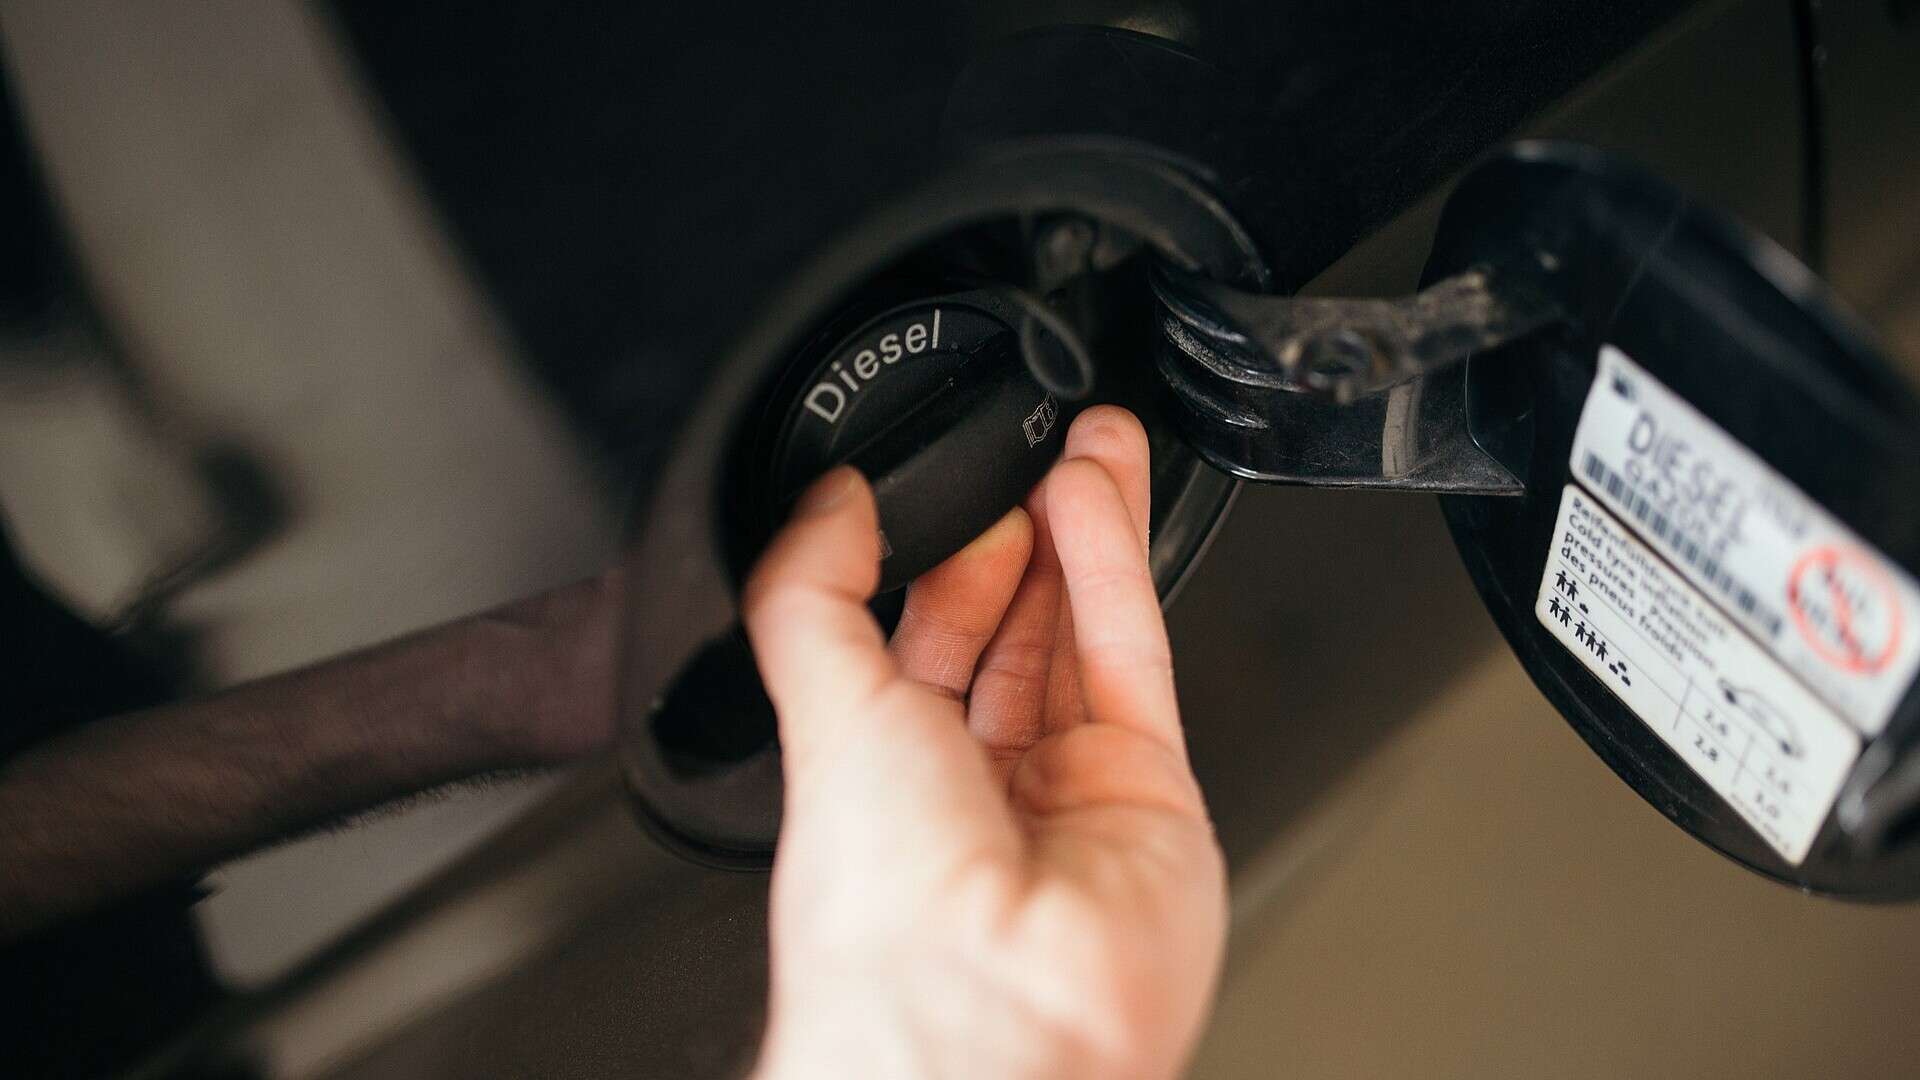
Federal diesel tax is normally collected when fuel leaves a terminal rack, well before it reaches a retail pump. Fuel headed for a nontaxable use, such as a combine, an excavator, or a furnace, can leave the rack untaxed if it is mechanically injected with Solvent Red 164. The IRS excise tax guide sets the dose at a concentration spectrally equivalent to at least 3.9 pounds of the Solvent Red 26 standard per thousand barrels, and requires the pump to carry the notice “DYED DIESEL FUEL, NONTAXABLE USE ONLY, PENALTY FOR TAXABLE USE.” The color lets an inspector with a sample jar tell in seconds whether a highway truck is running untaxed fuel.
When dyed fuel ends up in a highway vehicle anyway, the tax code has a backstop. Section 4041(a)(1)(A) imposes the highway rate on diesel sold to the owner, lessee or operator of a diesel-powered highway vehicle for use in that vehicle, and the tax falls on the seller. Section 4041(b)(1)(B) taxes fuel that was bought exempt for off-highway business use and then used some other way, which puts the liability on the user.
Those are the two taxes the order defers. The first covers the truck stop, co-op or bulk distributor that sells red diesel to a trucker. The second covers the farmer who fills a grain truck from the dyed-fuel tank behind the machine shed. A trucker buying from a retailer is not the taxpayer, so whether the deferral shows up as a lower pump price depends on retailers agreeing to sell fuel below a tax they may still owe when the deferral ends. Section 3 of the order requires Treasury’s guidance to state the date by which postponed taxes must be paid. As of Oct. 6, that guidance had not been posted.
The $100-per-refill claim, checked against the tax rate
The federal tax on highway diesel is 24.4 cents a gallon, according to the IRS guide. Deferring $100 of it takes 410 gallons. A driver who puts 200 gallons into a tractor defers $48.80.
The Energy Information Administration’s national average for on-highway diesel was $6.199 a gallon on Oct. 5, which makes the federal tax about 3.9% of the pump price. That average fell 18.3 cents from the week before but is $2.488 higher than a year earlier, so the deferral covers roughly a tenth of the past year’s increase.
The White House figure works for very large fills, or if states drop their own diesel taxes too. The order cannot do that. Section 8 directs the White House Office of Intergovernmental Affairs to encourage states to adopt matching policies, and Section 7 asks the Agriculture Department to encourage corresponding state action. USDA’s $640 million estimate includes state savings that depend on states acting.
Interstate truckers still owe the states through IFTA
For carriers that run in more than one state, the state tax shows up on the quarterly return filed under the International Fuel Tax Agreement. A carrier reports the fuel it burned in each member jurisdiction and owes each one at that jurisdiction’s rate, minus credit for fuel it bought with that jurisdiction’s tax already in the price. The IFTA Articles of Agreement grant the retail credit only when the purchase price included fuel tax paid to a member jurisdiction.
Red diesel bought without state tax earns no credit, and the miles still count. The carrier owes each state for that fuel on the fourth-quarter return, which under IFTA’s filing rule is due on the last day of the month after the quarter closes: Jan. 31, 2027. A truck that runs through a state without matching relief pays that state’s tax on the return instead of at the pump. A small fleet keeps that cash until the end of January, which helps with cash flow, but the liability stays on the books.
A disaster-relief statute is carrying the order
The IRS has let dyed diesel onto highways before. After Hurricane Sandy, it waived the dyed-fuel penalty for all of New Jersey and for New York City and four nearby counties from Oct. 30 through Dec. 7, 2012. Operators and sellers still had to pay the 24.4-cent tax. The IRS dropped only the penalties for missing semimonthly deposits.
This order goes further: it is nationwide and postpones the tax itself. The tool it relies on, section 7508A, lets Treasury disregard a period of up to one year for taxpayers affected by a federally declared disaster, a significant fire, or a terroristic or military action. Section 692(c)(2) defines military action as action involving the U.S. Armed Forces that results from violence or aggression, or the threat of it, against the United States or its allies. The fact sheet blames tight diesel supply on the Russia-Ukraine war and a worldwide lack of refining capacity. The order names no qualifying event. It leaves that finding to Treasury, by Oct. 10, in consultation with the secretary of war, which points toward the military-action category.
A 7508A deferral moves deadlines. Erasing a tax that Congress wrote into law takes Congress, which is why Section 4 mentions legislation.
EPA’s 15 ppm sulfur limit still governs what goes in the tank
The order deals only with taxes and leaves the EPA’s fuel-quality rules alone. Under 40 CFR 1090.80, diesel fuel includes any fuel used to power an engine designed to run on diesel, and 40 CFR 1090.305 caps diesel fuel at 15 parts per million sulfur. Off-road diesel for tractors and construction equipment has been held to that same limit since the EPA finished phasing in its nonroad, locomotive and marine fuel standards in 2014. At a farm co-op, red diesel is generally the same ultra-low-sulfur fuel as the clear diesel at the next pump, plus dye.
Heating oil is a separate product. The EPA defines it as fuel for furnaces, boilers and similar uses, outside the federal 15 ppm diesel standard, though some states set their own sulfur limits. Heating oil also moves tax-free, and much of it is dyed red. A truck owner who fills up from a heating-oil dealer’s tank could be feeding higher-sulfur fuel into an engine whose particulate filter and selective catalytic reduction system were built around ultra-low-sulfur diesel. Sulfur degrades those catalysts, and that repair bill goes to the truck owner, not the Treasury.
Harvest-season farms and highway fleets will share the same red tanks
Section 7 tells USDA to work with agricultural cooperatives, rural fuel distributors and farm supply organizations to make sure dyed diesel reaches farmers in high-demand areas. The order arrived during fall harvest, when farms burn the most dyed fuel. Letting highway trucks buy from the same tanks adds customers at the busiest time of year, and the order’s own text anticipates that some areas could run short.
Enforcement does not stop. Section 6 requires the Federal Motor Carrier Safety Administration to continue its audits, inspections and monitoring, and the IRS will announce how much attention it gives roadside fuel sampling during the relief period. The diesel order follows an FMCSA hours-of-service waiver for fuel haulers and a deal the White House says will release 100 million barrels of refined diesel from European strategic reserves over four months.
Dates for truckers and farmers to watch
Treasury’s findings are due by Oct. 10, followed by guidance that has to name the covered taxpayers and the date postponed taxes come due. After that, the evidence will be at the pump: whether retailers who sell red diesel to highway trucks price it 24.4 cents below clear diesel while still carrying the tax on their own books. State action will decide whether the $100 figure is reachable for anyone, and Congress will decide whether the deferral ever becomes a cut. For IFTA carriers, the first hard deadline is the fourth-quarter return on Jan. 31, 2027.
If you run a truck or a farm, would you fill up with red diesel this fall on the expectation that the deferred tax will be forgiven, or keep buying clear diesel and paying the 24.4 cents now?