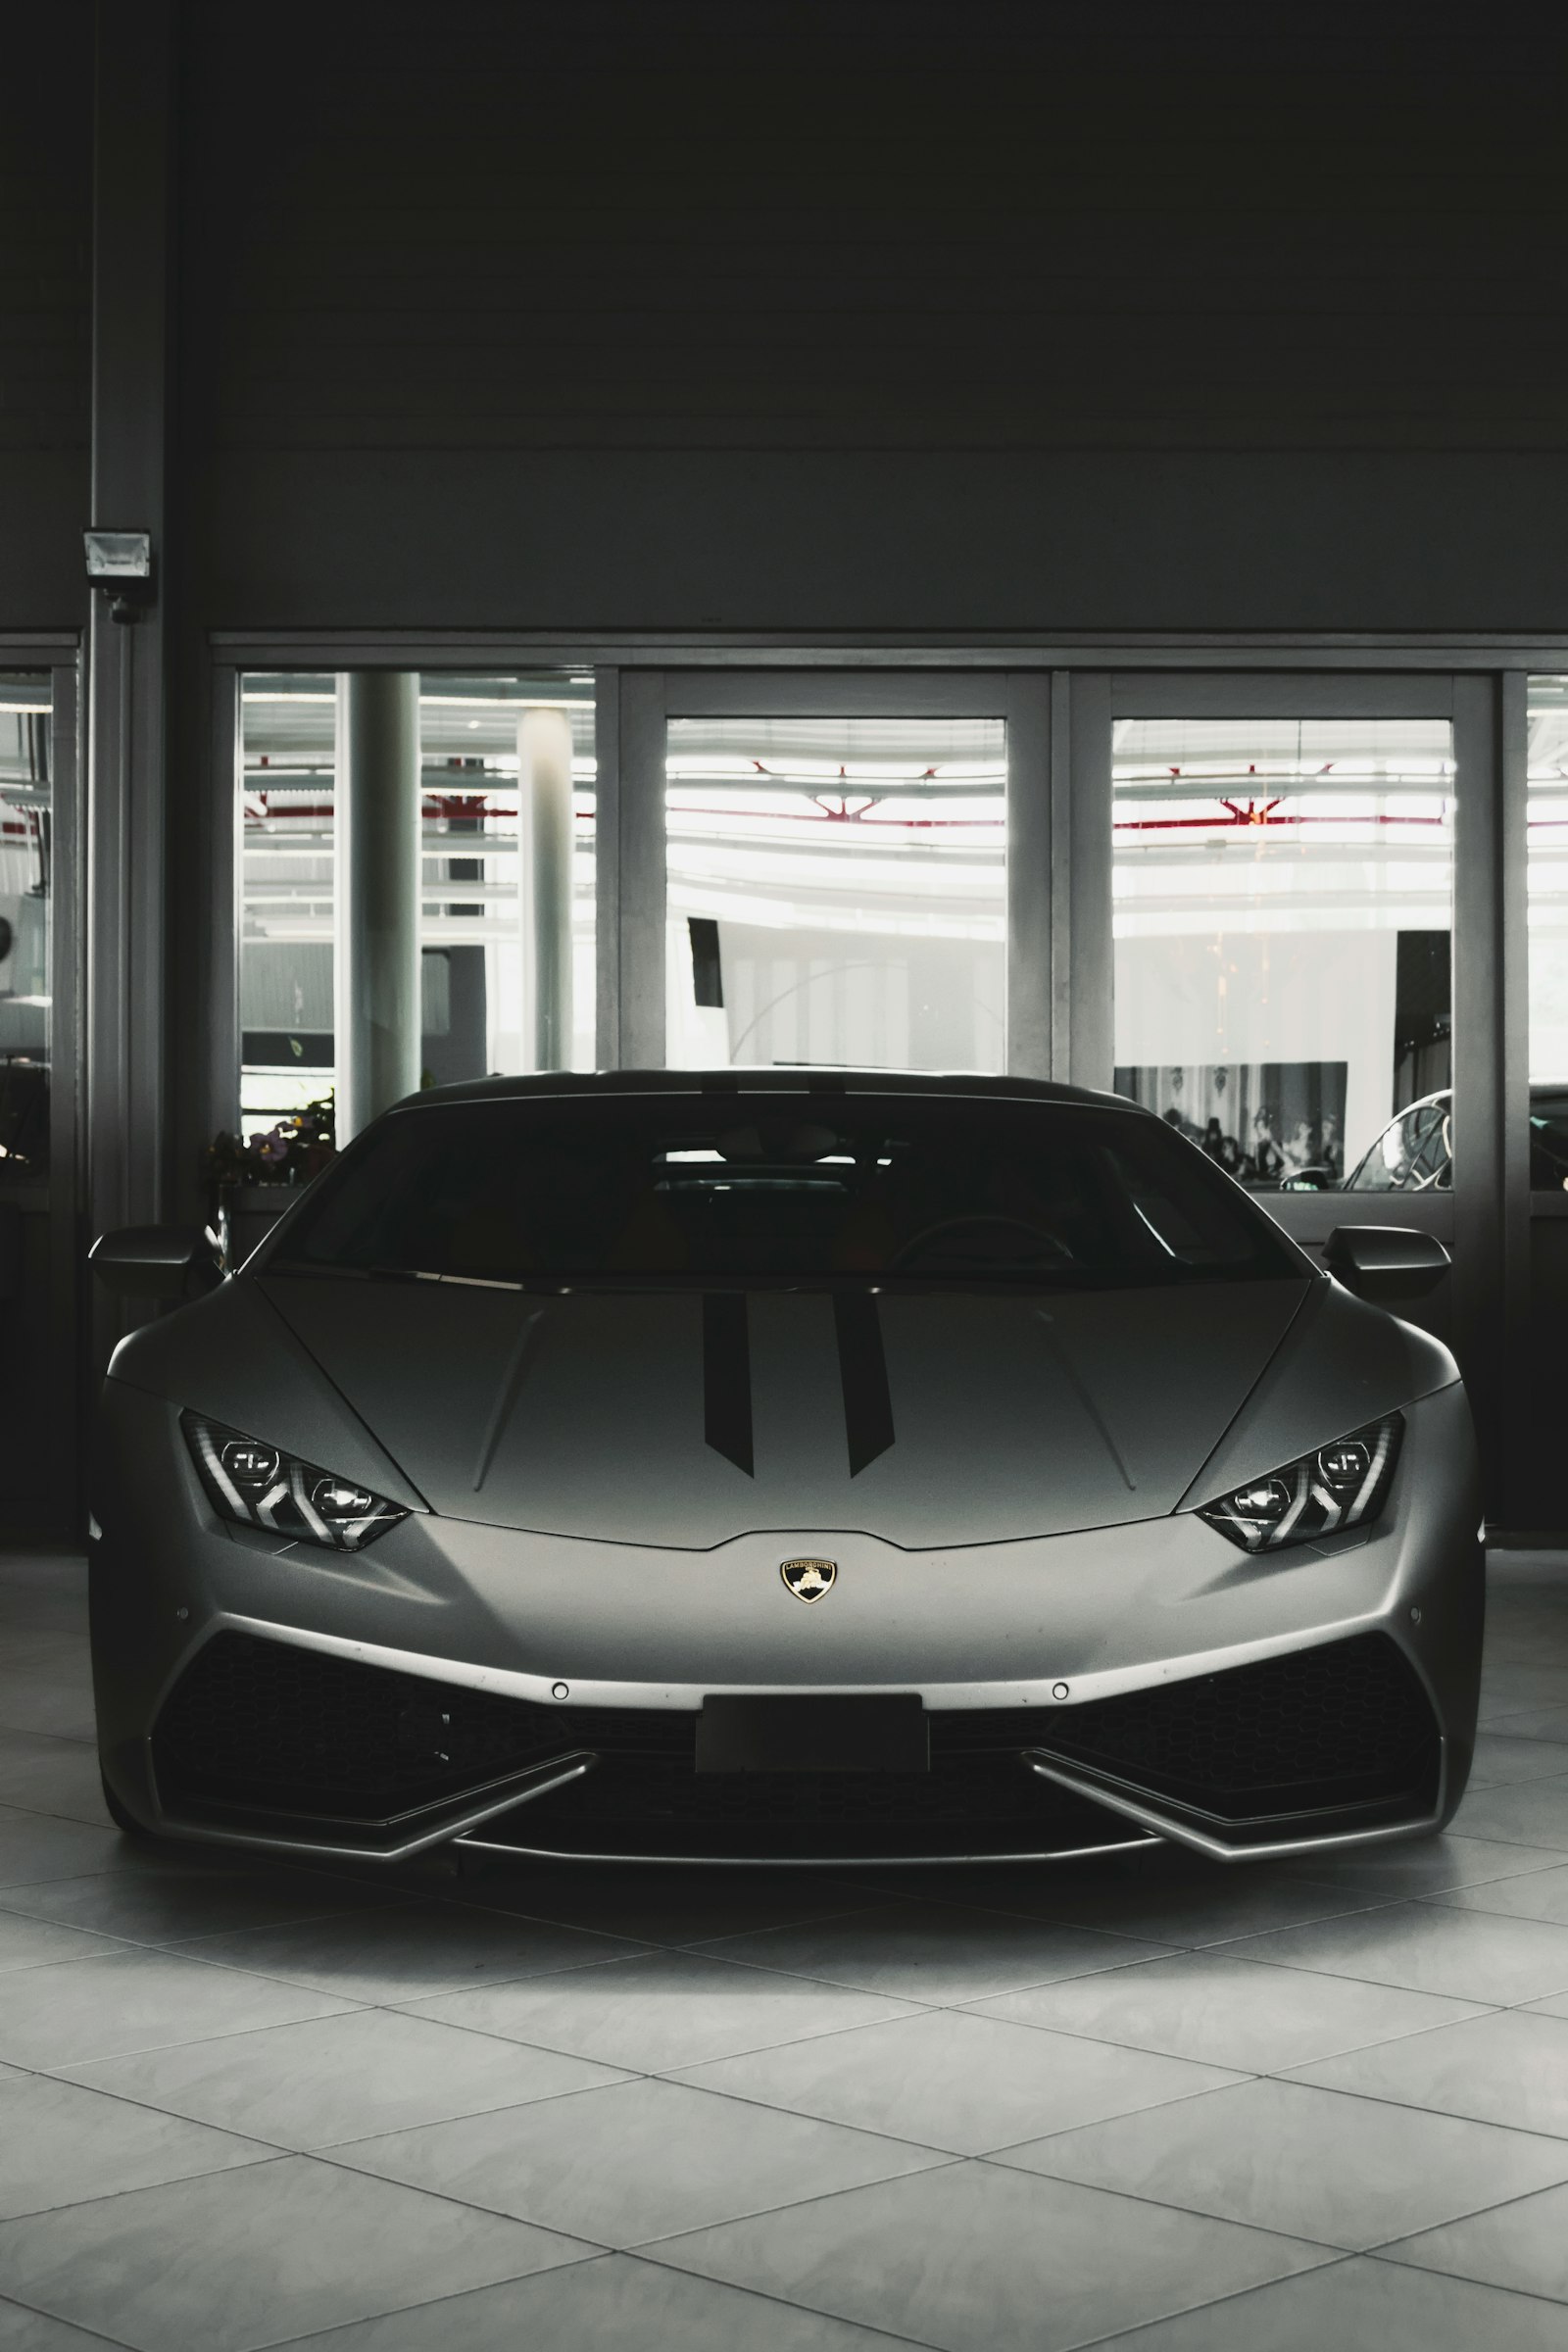
A New York man handed a Lamborghini to a dealer as part of an upgrade, and nearly lost both the car and about $200,000. He got the car back, and he has since helped investigators pursue the man who took it.
The part of this that should worry anyone who owns an expensive car is that he nearly lost it lawfully.
Not through a loophole. Through a rule that American commercial law adopted on purpose, and that says in plain words that it applies even when the person selling your car is committing a crime.
A note on the case
The Auto Wire could not verify the criminal case from a primary source. We checked the New York Attorney General’s press releases, the US Attorney’s offices for the Eastern and Southern Districts, and the district attorneys’ offices for Suffolk, Manhattan, Brooklyn and several Capital Region counties, and found no matching prosecution on the public record.
So we are not going to print a defendant’s name, a charge or a docket number we have not seen. We covered the underlying situation last September, and the follow-up detail that he assisted in catching the scammer remains unconfirmed.
What can be documented in full is the machinery — how the scheme works, and why the law makes it so dangerous for the owner. That is the useful part anyway, because it applies to every reader who is ever tempted to leave a car on consignment.
The moment you hand over the keys, the law reclassifies your car
Here is the doctrine, and it is worth reading slowly.
Under Uniform Commercial Code section 2-403(2): “Any entrusting of possession of goods to a merchant who deals in goods of that kind gives him power to transfer all rights of the entruster to a buyer in ordinary course of business.”
Then subsection (3) defines entrusting, and this is the sentence that decides these cases: it “includes any delivery and any acquiescence in retention of possession regardless of any condition expressed between the parties to the delivery or acquiescence and regardless of whether the procurement of the entrusting or the possessor’s disposition of the goods have been such as to be larcenous under the criminal law.”
Read the two clauses at the end. Your consignment agreement — do not sell below this price, pay me within ten days, do not transfer title without my signature — is a condition expressed between the parties, and the statute says conditions do not matter. And if the dealer’s disposal of your car amounts to larceny, the statute says that does not matter either.
A dealer can steal your car and still pass clean title to an innocent buyer. That is not a failure of the law. That is the law, written down, deliberately.
And knowing about the lien does not save you
The second doctrine closes the other escape route.
The default rule under UCC 9-315 is comforting: a security interest continues in collateral notwithstanding sale. The lien follows the car.
Then UCC 9-320(a) carves an exception that swallows it: “a buyer in ordinary course of business… takes free of a security interest created by the buyer’s seller, even if the security interest is perfected and the buyer knows of its existence.”
Even if the buyer knows. Actual knowledge of the lien does not defeat the buyer.
A buyer in ordinary course is someone who buys in good faith, without knowledge that the sale violates another person’s rights, from a person in the business of selling goods of that kind. Buying a Lamborghini from a Lamborghini dealer is the textbook case.
Put it together and the picture is stark. The person who hands a supercar to a dealer holds an unsecured contractual claim. The stranger who buys it holds a car.
Why the law was built this way
It sounds like an injustice until you consider the alternative.
If a buyer had to verify that every car on a dealer’s lot was truly the dealer’s to sell — tracing consignment agreements, floor plan liens and title history before every purchase — the retail vehicle market would seize up. The rule exists so that ordinary people can buy from a dealer with confidence.
The drafters made a choice: a stranger’s ability to buy safely from a merchant outranks an owner’s ability to recover a car he voluntarily handed over. Commerce over possession.
The owner who almost lost his Lamborghini did not fall through a crack. He ran into a design decision.
How the scheme runs, and why it is usually a cash-flow story
The mechanics are documented in regulators’ own language.
Start with what a dealer does with a consigned car. The Federal Trade Commission requires a Buyers Guide displayed on used vehicles for sale “through consignment, power of attorney, or other agreement.” To the federal government and to every passer-by, your car on their lot is simply inventory.
Now the money. Dealers finance inventory through floor plan lending, borrowing against each vehicle. The Office of the Comptroller of the Currency’s handbook names the failure mode: “A dealer sells out of trust when the inventory is sold and the funds are not immediately remitted to the bank to retire the corresponding debt.”
It goes further, describing the tell examiners look for: if inventory is missing at inspection and the dealer then pays, “it is a sign that the dealer may be taking advantage of a float, i.e., using proceeds of inventory possibly sold weeks before the inspection.”
That is a banking regulator describing robbing Peter to pay Paul. And in an exotic car dealership, the customer is Peter.
Exotic inventory moves slowly, so floor plan loans come due on cars that have not sold. A dealer facing those payments has a recurring, urgent cash need — and a consigned customer car carries no debt at all. It is the cheapest money in the building.
Most consignment fraud is not a plan to steal one car. The same pattern shows up when a dealer runs out of money before it runs out of customers. It is a liquidity crisis metastasising, with customers as the last unsecured creditors to find out.
The bond is nowhere near the size of the car
When it collapses, the remedy is a surety bond, and the arithmetic is the scandal.
New York requires a dealer selling more than 50 vehicles a year to post a $100,000 bond. A dealer selling 50 or fewer posts $20,000. Franchised new-car dealers post $50,000.
A Lamborghini Huracán is worth roughly twice the maximum bond any New York used car dealer must carry. And the bond form caps total liability “for all breaches of the Bond condition… to the face amount of the Bond” — shared among every victim, not per claim.
You must also first win a judgment before you can reach it.
The state’s bond regime was calibrated for eight-thousand-dollar used sedans. It is the only financial backstop standing behind a six-figure exotic, and it is shared.
The motor vehicle department has a separate track, but note how it is framed: outcomes range from no action through warnings, suspension, revocation and civil penalties, and a dealer “may also be offered the opportunity to pay restitution to the consumer instead of the fines.” Restitution is an alternative to fines, offered to the dealer. It is not a consumer right.
The federal tool aimed at the wrong risk
Buyers face the mirror image of this problem too — fake dealership websites are targeting classic car buyers. The standard advice is to run a history check, and the official tool is the National Motor Vehicle Title Information System, run by the Justice Department’s Bureau of Justice Assistance, at up to $4 a report.
It returns five things: current title status and date, brand history such as junk, salvage or flood, odometer reading, total loss history and salvage history.
Read that list again for what is missing. The government’s own explanation of the report does not list liens. NMVTIS is a title-brand and theft tool. It is not a lien search, and it will certainly not tell you whether the dealership holding your car is floor-planned to the ceiling.
The official consumer protection database is aimed at a different crime than the one that takes supercars.
What actually protects you
Built from the primary sources, the checklist is short and unglamorous.
Check the dealer’s licence and, specifically, which bond tier they are in. A $20,000-tier dealer is not a safe home for a $200,000 car, and that is a public fact you can look up.
Require any lien payoff to be wired directly to the lienholder. Never through the dealer. In New York a security interest is perfected by delivery of the title or application to the Commissioner, and dates from creation only if delivered within ten days — so confirm the release was actually filed, in that window.
Demand written proof that the replacement car exists, is owned by the dealer, and is unencumbered, before your car leaves your possession. An upgrade is two transactions, and the scheme lives in the gap between them.
And understand the thing most owners get wrong: your consignment agreement protects you against the dealer. It protects you against nobody else.
What to remember
Forget the section numbers. Remember one clause.
American commercial law says that entrusting your car to a dealer gives him the power to sell it “regardless of whether… the possessor’s disposition of the goods have been such as to be larcenous under the criminal law.”
The law anticipated that the person holding your car might be a thief, and decided the buyer should win anyway.
Which means the moment those keys change hands, you no longer own a car. You own a promise.
Should the law close this loophole? Sound off in the comments.